Andrew Malm NMLS# 2663426 · Powered by Edge Home Finance, LLC NMLS# 891464 · Equal Housing OpportunityCall 763-373-9360Text me
PURPOSEHOME LOANSpowered by Edge Home Finance, LLC
CallTextApply

Home loans

Your home.
Your right loan.

Going to one bank means seeing one set of options. I shop your file across 100+ lenders, then explain every step in plain language. I am licensed in Minnesota and Wisconsin, and home loans in other states are available through the licensed team at Edge Home Finance, LLC, with me as your point of contact.

Seeing your options takes no hard credit pull, so your score is not affected. About 60 seconds.

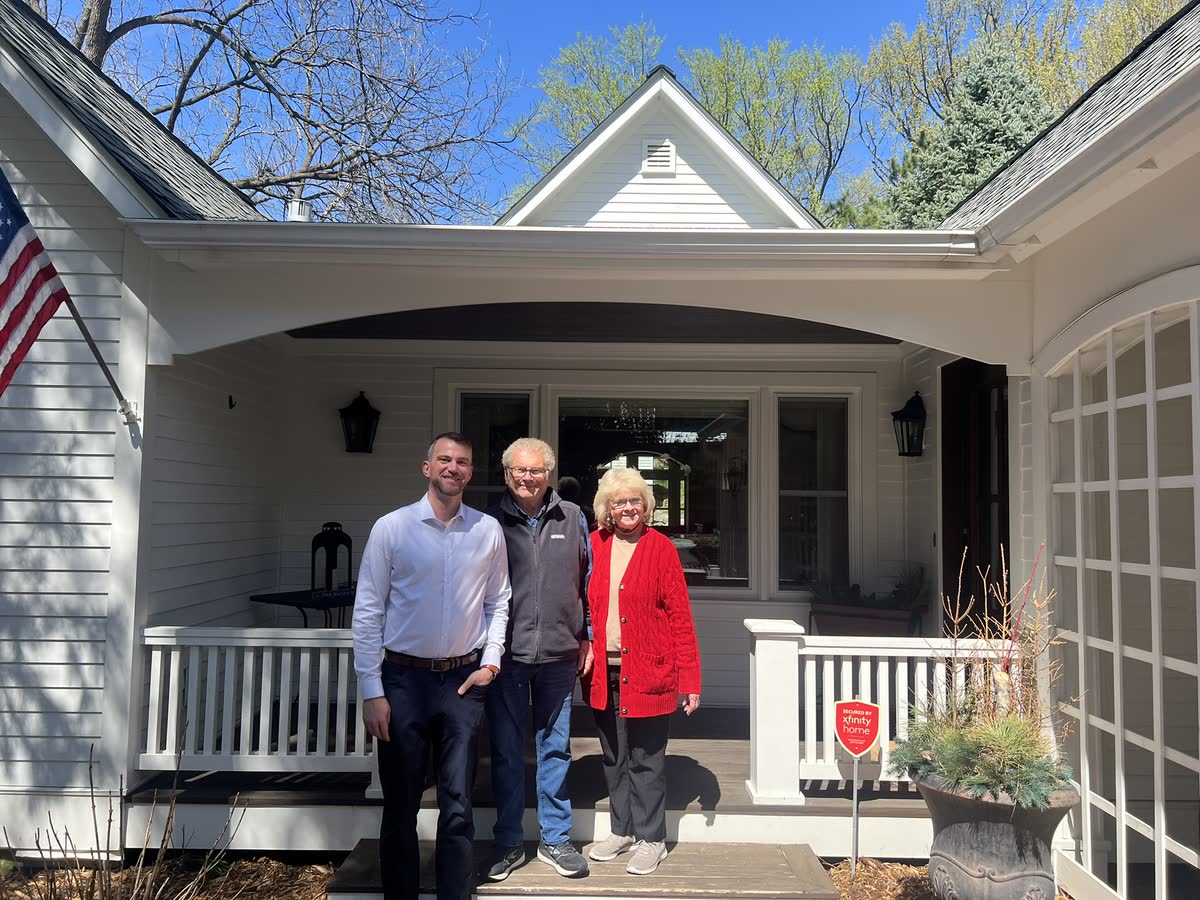
Andrew Malm with clients on the porch of their new home
Closing day. A bank once told us no on our own home, and a broker found the yes. Read the story

Already under contract?

Get a second look at your Loan Estimate.

If you're under contract and holding a Loan Estimate from another lender, text me a photo of it. I'll compare it against my lenders and tell you straight whether I can do better. If I can't, I'll say so, and you keep your lender.

Feel free to cover your name and loan number before you send it.

Step 1

Application

About fifteen minutes online, or call me and I'll walk you through it.

Step 2

Pre-approval

Documents reviewed first, so the letter means something to a seller.

Step 3

Close

I keep you posted at every step. No surprises at the closing table.

Find the program built for your situation.

These are the most common paths, and with 100+ lender relationships there are many more behind them. Self-employed? Your write-offs are not the end of the story.

Conventional

Standard purchase financing for buyers with strong credit profiles. Fixed and adjustable options.

FHA

Built for first-time buyers and buyers whose credit is still a work in progress. Government-backed, flexible qualification.

VA

For veterans and service members. Earned, not given. No monthly mortgage insurance.

USDA

For eligible rural and suburban properties, with low down payment options for buyers who qualify.

Jumbo

Above conventional loan limits. I work with lenders who specialize in large-balance purchases.

Refinance

Lower the payment, shorten the term, or access equity. I'll tell you honestly if a refinance makes sense, and honestly if it does not.

Home equity line of credit

Flexible, revolving access to the equity you have built, without touching your first mortgage. A HELOC is secured by your home.

Buy before you sell

Programs that let you make a non-contingent offer while you still own your current home.

Renovation

Purchase and repairs in one loan, for the home that needs work.

Two deals, the way they actually went.

More stories

Coffee at the kitchen table

He called because the online application was winning. An older gentleman, sharp as anyone, and not about to photograph his bank statements with a phone. I get it. So I drove over. We had coffee at his kitchen table, and in one afternoon every document was in.

Then he told me he only meant to keep the loan about a year. That is not a thirty-year problem. We built it so he put the least cash down up front.

The right loan depends on your plan, not the lender's menu.

Same loan, thousands less at the table

She knew exactly what she wanted. Another lender had priced it so high the deal barely made sense. The structure was fine. The price was not.

I found the same structure at a far lower cost. She kept the loan she wanted, saved thousands at closing, and we closed in under twenty days.

Shopping the loan is the minimum. Shopping the cost of the loan is the job.

Real clients, details changed for privacy. Every loan is different.

Payment, affordability and refinance, right here.

Adjust the inputs to match your situation. Every estimate updates as you type, and nothing here asks for your email.

Monthly payment

Full PITI estimate: principal & interest, taxes, insurance, mortgage insurance and HOA, with amortization and extra-payment payoff.

Loan details

$
%
$
%

Taxes, insurance & extras

$
$
$
%
$
Total monthly payment
…
…

Payment breakdown

Amortization (yearly)

How much home can you afford?

Three budgets from your income and debts: the conservative 28/36 rule, a moderate 43% DTI, and the aggressive end of what underwriting allows.

Income & debts

$
$
$
$

Loan assumptions

%
% of price
% of price
Debts = minimum monthly payments on cards, auto and student loans, not utilities or groceries. PMI is added automatically when the down payment is under 20%.

Where each budget comes from

Refinance break-even

Monthly savings, months to recoup closing costs, and the lifetime-interest comparison most calculators skip. Resetting to a new 30-year term can lower the payment while raising total interest.

Current loan

$
%
yrs

New loan

%
$
yrs
Monthly savings
…
…

Total cost comparison

Estimates for illustration only, not a loan offer or rate quote. Pre-filled values are adjustable sample inputs, not offered terms or an advertisement of credit. See all the calculators at the calculators page.

Questions home buyers ask most.

No jargon. Plain answers to the questions I hear every week.

What's the difference between a mortgage broker and a bank?
A bank can only sell you its own products, so you see one set of options and one set of guidelines. Through Edge Home Finance, LLC, a mortgage broker, I shop your scenario across many lenders at once and bring you the options that fit. More options compared, trade-offs explained before you choose.
How much do I need for a down payment?
It depends on the program, and some programs need far less than people assume. VA and USDA loans have low down payment options for buyers who qualify. Tell me your situation and I'll show you what the programs you qualify for actually require, not the textbook answer.
What credit score do I need to buy a house?
Programs differ, and the minimum on paper is not the same as the score that gets the best terms. Tell me your score and I'll tell you which doors are open, and if the answer is not yet, exactly what would change it.
Pre-qualification or pre-approval: which one do I need?
Pre-qualification is an estimate from what you tell me. It does not mean much to a seller. Pre-approval involves a credit pull and a document review, and it carries real weight in a competitive offer. I review documents before the letter goes out, so it means something.
What are closing costs and who pays them?
Lender fees, title, appraisal, and prepaid items like insurance and taxes. Some are negotiable, some can be covered by seller concessions, and some can be rolled into the loan depending on the program. You get a full estimate up front.
Does it cost me anything to use a mortgage broker?
Usually the lender pays me, not you, and that compensation is disclosed to you in writing in your loan disclosures. Lender-paid does not mean the loan is free: every mortgage has costs, and you see all of them before you commit. Some structures have the borrower pay the broker directly instead. I'll always show you how I am compensated on your specific loan.
How long does the mortgage process take?
A typical purchase runs a few weeks from application to close, and refinances can be faster. I set a clear timeline at the start and flag issues before they become problems.
Do I need to live in Minnesota or Wisconsin to work with you?
No. I am licensed in Minnesota and Wisconsin. For home loans in other states I stay your point of contact and work through the licensed team at Edge Home Finance, LLC, who handle credit, disclosures and pricing in that state. Investor loans are available in most states. Licensing coverage varies by loan program and lender. Not all programs available in all states.

More questions? Read the answers, or text me yours.

Ready to see where you stand?

One conversation: programs, what you need, timeline. No pitch.