Andrew Malm NMLS# 2663426 · Powered by Edge Home Finance, LLC NMLS# 891464 · Equal Housing OpportunityCall 763-373-9360Text me
PURPOSEHOME LOANSpowered by Edge Home Finance, LLC
CallTextApply

Investor loans in 49 states and D.C.*

Your first deal.
Your next ten.

Fix and flip, DSCR rentals, equity and bridge loans, and ground-up construction. Tell me about the deal and I'll tell you which programs fit and what the honest numbers look like.

No hard credit pull for the review, so your score is not affected. About 60 seconds.

1. Send me the deal

Address, price, and the plan. About five minutes.

2. See your options

The programs that fit, with the trade-offs explained.

3. Close

14 to 21 days on a clean deal. More complex deals can take longer.
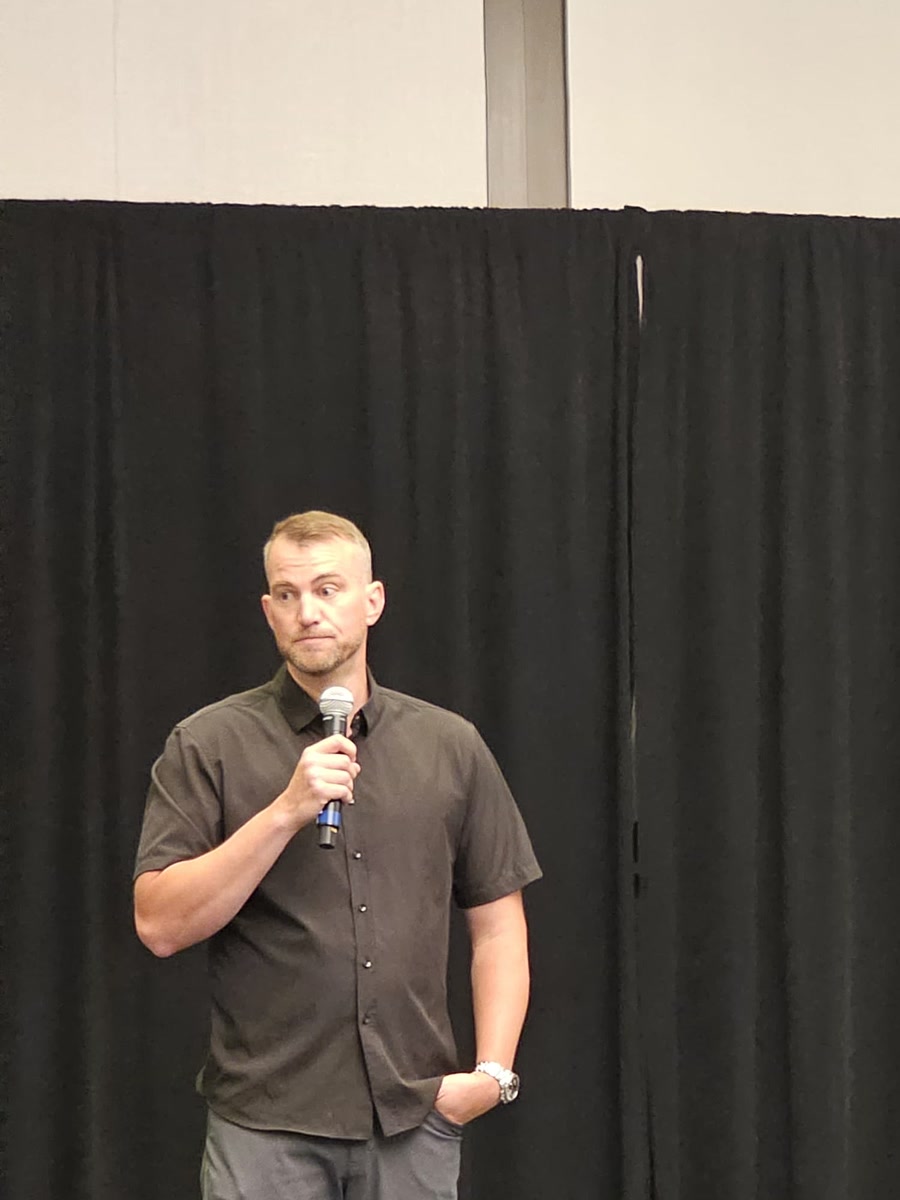
Andrew Malm on stage at an investor event

Why it matters who you call

It's not the car.
It's the driver.

Investor lenders all look alike on a rate sheet. The difference shows up when the appraisal comes in low or the draw schedule slips. That is when it matters who is driving your deal.

I'll fight to get your deal across the line.

What I fund.

Start with what you are trying to do. I'll tell you which program fits your deal.

Buy it and fix it

Fix and flip

Short-term money sized on the deal: the price, the rehab budget, and what it is worth finished.

Purchase plus rehab

Fix and flip loans

Purchase and renovation in one loan, sized on the deal, not your personal income.

First flip

Programs for first-timers

Some programs consider a first flip. Every finished project becomes experience the next lender counts.

The exit

Flip to rental

Finish the rehab, lease it, and refinance into a long-term rental loan. I plan the exit before the purchase.

Buy it and hold it

Rental loans

Long-term loans that qualify on what the property earns.

1 to 4 units

DSCR rental loans

Qualify on the property's rent, not your tax returns. Built for growing a portfolio without piling paperwork on every deal.

5 to 8 units

Small multi-family

Rental underwriting on a bigger building, without a full commercial loan.

By the night

Short-term rentals

Programs that count short-term rental income, for the property that earns by the night.

Use what you already own

Unlock capital

The equity you have built can fund the next deal. Each of these is secured by the property, so I run what the cash costs against your plan first.

From a rental

Cash-out refinance

Replace the loan on a rental with a larger one and take the difference in cash.

From a rental

Line of credit on a rental

A HELOC against an investment property, in first or second position. A second leaves a low-rate first mortgage alone.

From your own home

Equity in your primary home

A line of credit or a cash-out refinance on the home you live in, to fund the next purchase. It is secured by your home.

Short-term

Bridge loans

Buy before the sale or the permanent financing is in place, then pay it off when it is.

Start from the ground

Build

For the investor who is ready to build instead of buy.

Ground-up

Construction loans

Builds to sell or to rent. Some programs will consider a first build when a licensed, experienced general contractor runs the project.

5 to 20 units

Small multi-family construction

Construction and permanent financing planned together.

The lot

Land loans

Buy the lot now and build later. Land is a narrower market, so tell me the parcel and the plan first.

Not sure which one is yours? Send me the deal and I'll tell you.
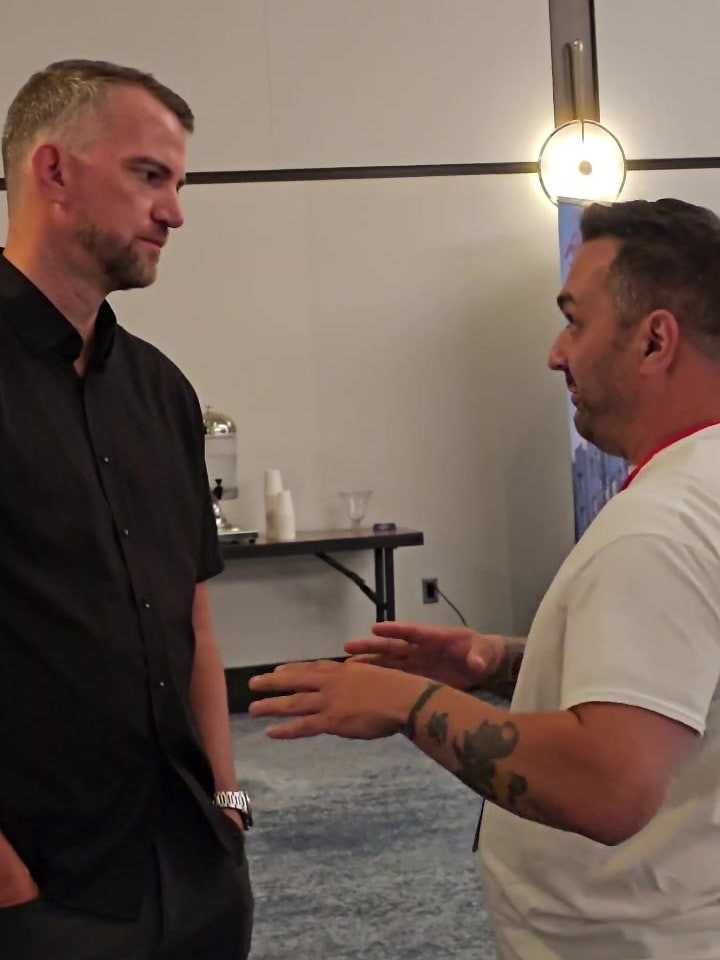
Andrew Malm listening to an investor describe a deal

What working with me looks like

Before you ask a lender for money.

Most of my investor work happens before the application. Getting you ready to ask is the job. Here is what we work through together.

01
Credit and cash
Where they are, where they need to be, and the fastest honest way between the two.
02
The numbers
Price, budget, and what it is worth or rents for when you are done. I run them the way the lender will.
03
Your team and your structure
Contractor, entity, draws and the exit, laid out the way a lender reads them.
04
Whether you need a partner
Experience, money or credit. Sometimes the right partner is the difference between a no and a yes.

Run your numbers.

The same math I run on every deal. Free, and nothing asks for your email.

DSCR rental loan

Lender math: gross rent ÷ PITIA, qualifying on the lower of lease or market rent, with the interest-only variant and a max-loan solver at your target ratio. Investor cash flow shown separately: vacancy and management never enter the lender's ratio.

Property & loan

$
%
%
×

Rent

$
$

Expenses

$
$
$
% of price
%
%
%
Qualifying DSCR
…
…

Lender qualification

Investor cash flow (not in the lender ratio)

Fix & flip analyzer

Loan sized as the lesser of loan-to-cost and loan-to-ARV with 100% rehab financed, Dutch or as-drawn interest, the full cost stack through resale, and the max offer worked backward from your target profit.

The deal

$
$
$
%
mo
% of ARV

Financing

%
%
%
pts
$
$

Other costs

% of price
$
% of ARV
Net profit
…
…

Loan sizing

Full cost stack

Maximum offer

Ground-up construction

New-build pro forma: land plus hard, soft and contingency costs, loan sized on LTC vs completed value, interest on average drawn balance, and a build-to-sell or build-to-rent exit.

Project budget

$
sq ft
$
% of hard
% of hard
$

Financing

%
%
%
pts
%

Sale assumptions

% of value
Projected profit
…
…

Loan sizing

Project cost stack

Exit

Estimates for illustration only, not a loan offer or rate quote. Pre-filled values are adjustable sample inputs, not offered terms or an advertisement of credit. See all the calculators at the calculators page.

Questions investors ask most.

What do you need from me to review a deal?
The address, the price, and the plan. For a flip, add the rehab budget and what you expect it to be worth finished. For a rental, add the expected rent. For a build, the lot, the budget, and who is building it. Tell me your experience and whether you are buying in an LLC, and I can usually tell you which programs fit in one conversation.
What is a DSCR loan and who is it for?
A loan that qualifies on the property's rental income instead of your personal income. If the rent covers the payment, the deal can work. It fits self-employed investors, W-2 earners with several properties, and anyone growing a portfolio without piling paperwork on every deal.
Can I get a loan for my first flip or my first rental?
Often, yes. Some programs consider first-time investors, usually with more cash in the deal or a stronger credit profile than they ask of an experienced investor. Tell me what you have done so far, even if that is nothing yet, and I'll tell you where you stand.
How much cash do I need to bring?
It depends on the program, your experience and the deal, so I will not quote a number on a web page. Plan on a down payment, closing costs and some reserves. On a flip or a build, the rehab or construction budget is usually paid out in draws after the work is done, so you also need cash to carry the work between draws. I lay out the full cash to close before you commit to anything.
How do rehab and construction draws work?
The lender holds the renovation or construction budget and releases it in stages. You finish a stage, an inspector confirms the work, and the lender reimburses you. You or your contractor carry each stage until the draw arrives, so the draw schedule matters as much as the rate. I go through it with you before closing.
Can I pull cash out of a property I already own?
Often, yes. A cash-out refinance replaces the loan on the property with a larger one. A line of credit leaves your first mortgage alone and lets you draw as you need it. Either can work on a rental, and on your own home too. Both are secured by the property, so I compare what the cash costs against what you plan to do with it, and I'll tell you if the math does not work.
What is the difference between hard money, private money and a bank loan?
Hard money and private money are mostly two names for the same thing: short-term loans sized on the deal, quick to close, and priced higher than a bank. A bank loan costs less and asks for more: more documentation, more time, and a closer look at you. Many investors buy and fix with the first, then refinance into long-term financing. I'll show you both paths side by side.
Can I close in an LLC?
Yes. Most investor programs, including DSCR, fix and flip, bridge and construction, allow closing in an LLC, a corporation, or in some cases a trust.
How fast can you close?
14 to 21 days on a clean deal. More complex deals, construction especially, can take longer. I set a realistic date up front and tell you the moment anything moves it.
Do I need experience to get a construction loan?
Not always. Some programs do not require prior builds when a licensed, experienced general contractor runs the project. Your credit, your cash and the deal itself still have to qualify, and I'll tell you where you stand before you spend money on plans.
Can you lend where my property is?
Most likely. Investor programs are available in most states, and coverage depends on the program and the lender. Tell me where the property is and I'll confirm before you spend any time on it.*
Is there a cost to get a deal reviewed?
None. Send me the deal, call, or text. No hard credit pull is required to start. A credit review is required for a formal application, but we do not start there.

More questions? Read the answers, or text me yours.

Got a deal? Let's pressure-test it.

Tell me the address, the price, and the plan.